Quick Answer: Should you pay off your rental property or invest in another one?
If a second rental cash flows from day one, investing in another property usually builds more wealth than paying off your rental property. In our Birmingham example below, buying a second rental put an investor about $42,000 ahead after 10 years. Paying it off may make more sense if you want less risk or can’t find a property that cash flows.
Join RealWealth for free to see current cash-flowing properties for sale.
Should you pay off your rental property or invest that cash in another property and keep growing your portfolio? It’s a question many investors face once their first rental is up and running. A paid-off property means more monthly income and fewer worries. On the other hand, that same cash could help you buy a second rental and build wealth faster.
Rather than rely on opinions, we ran both options through a model using current prices, rents, and expenses from real RealWealth markets. In this article, you’ll find:
- A side-by-side comparison of paying off your rental property vs. investing in another one
- How the results hold up when the market underperforms
- The pros and cons of paying off a rental mortgage early
- Ways to lower your risk if you decide to keep your mortgage
Pay Off Your Rental Property or Invest in Another? Let’s Run the Numbers
To compare both options fairly, we started with the same situation:
- You own one rental property that still has a mortgage
- You have $39,200 in cash to put to work
- You can use that cash to pay down your mortgage, or as a down payment on a second rental
To see which option comes out ahead, we looked at what you’d walk away with if you sold at the 10-year mark, and again at 30 years. That includes your equity after selling costs, plus all the cash flow you collected along the way.
What Numbers Did We Use?
We used current prices and rents for single-family homes in Birmingham, Alabama, one of RealWealth’s cash-flow markets. Where we had to make an assumption, we leaned conservative.
| Input | What We Used |
|---|---|
| Property price | $140,000 for each rental |
| Rent | $1,350 a month, rising 3% a year |
| Appreciation | 3% a year |
| Rental #1 loan | Bought three years ago, 25% down, 6.5% rate |
| Rental #2 loan | 25% down at 7.5%, plus 3% in closing costs |
| Vacancy, management, and repairs | 5%, 8%, and 8% of rent |
| Property tax and insurance | 1.0% and 0.7% of the home’s value each year |
| Extra cash flow | Added up as cash, with no investment return |
Why 7.5% for the new loan? As of October 2026, strong borrowers with excellent credit were seeing quotes around 7.5% on Bankrate’s investment property rate tables, often after paying points. Your rate will depend on your credit, down payment, and lender, which is one reason it pays to use RealWealth’s recommended lenders who understand real estate investing.
What about the extra cash flow? That’s up to you. You could:
- Save it toward your next rental
- Pay down other debt
- Keep it in a high-yield savings account
To keep the comparison simple, we added it up without assuming any return.
What About Selling Costs and Taxes?
Since we’re measuring what you’d walk away with after selling, we take 6% off the property values at the end. Selling a property isn’t free, and in the second scenario, you’d be selling two homes instead of one.
That 6% covers:
- Agent commissions: These average about 5.5% nationally, according to Clever Real Estate’s 2026 survey.
- Other closing costs: Sellers usually pay a few, like title fees.
Commissions are also more negotiable than they used to be. Since a 2024 legal settlement, sellers no longer have to offer a set fee to the buyer’s agent. Most still do, though.
We left taxes out of the numbers since they depend on your situation, but they’re worth understanding:
- Depreciation: This is a yearly write-off for wear and tear on the building. If about 80% of a $140,000 rental’s price is the building (land doesn’t count), that’s roughly $4,000 a year you may be able to deduct. A second rental doubles it.
- Mortgage interest: It’s generally deductible against your rental income, so two loans mean more write-offs.
- Taxes when you sell: The IRS takes back some of that depreciation through recapture, and two properties mean more capital gains. That is why strategies like a 1031 exchange are so popular with investors: they let you defer those taxes.
How much any of this helps depends on your income and plans, so it’s worth running the numbers with a CPA who works with real estate investors.
Scenario 1: What Happens If You Pay Down Your Rental Property Mortgage?
Let’s start with the option that feels safer. Your rental is worth about $140,000 today. You still owe roughly $92,600, and your principal and interest payment is $607 a month.
You send your lender a check for $39,200. Your balance drops to around $53,400, and if you keep paying that same $607, the loan is gone in about 10 years. Without that extra payment, you’d be making payments for another 27.
In the meantime, the property nets you about $261 a month after expenses. Once the loan is paid off, that $607 stays with you, and your monthly cash flow more than triples.
Your equity grows along the way, too. Right after that $39,200 payment, you have about $86,600 in equity. As the property appreciates and your payments wipe out the loan, that climbs to roughly $188,100 by year 10, all of it yours, free and clear.
Scenario 2: What Happens If You Buy Another Rental Instead?
Same $39,200, different plan. This time it covers a 25% down payment ($35,000) plus closing costs ($4,200) on a second $140,000 rental in the same market.
The new $105,000 loan at 7.5% comes with a principal and interest payment of about $734. Will the rent cover it? In Birmingham, yes, with some to spare. Once the mortgage, management, repairs, taxes, and insurance are paid, you’re left with about $134 a month. Pair that with the $261 from your first rental, and your two properties are putting roughly $395 in your pocket every month.
Yes, you’re carrying two mortgages now. But your tenants are paying both of them down, and you’ve got two properties appreciating instead of one. At the 10-year mark, they’re worth about $376,300 combined. Subtract the roughly $166,000 you still owe, and that leaves about $210,300 in equity.
Which Option Comes Out Ahead?
Here’s where you start: Rental #1 is worth $140,000, you owe about $92,600, and you have $39,200 in the bank. That’s roughly $86,600 to your name before you decide anything.
Scenario 1: Pay down Rental #1
| Starting point | After 10 years | After 30 years | |
|---|---|---|---|
| Property value | $140,000 | $188,100 | $339,800 |
| Loan balance | -$53,400 | $0 | $0 |
| Equity | $86,600 | $188,100 | $339,800 |
| Selling costs (6%) | n/a | -$11,300 | -$20,400 |
| Cash flow collected | $0 | $46,600 | $422,800 |
| Net worth | $86,600 | $223,500 | $742,300 |
Scenario 2: Buy Rental #2
| Starting point | After 10 years | After 30 years | |
|---|---|---|---|
| Property value (both rentals) | $280,000 | $376,300 | $679,600 |
| Loan balance (both rentals) | -$197,600 | -$166,000 | $0 |
| Equity | $82,400 | $210,300 | $679,600 |
| Selling costs (6%) | n/a | -$22,600 | -$40,800 |
| Cash flow collected | $0 | $77,900 | $530,200 |
| Net worth | $82,400 | $265,600 | $1,169,100 |
Notice that Scenario 2 starts a little behind. That’s the $4,200 you spent on closing costs.
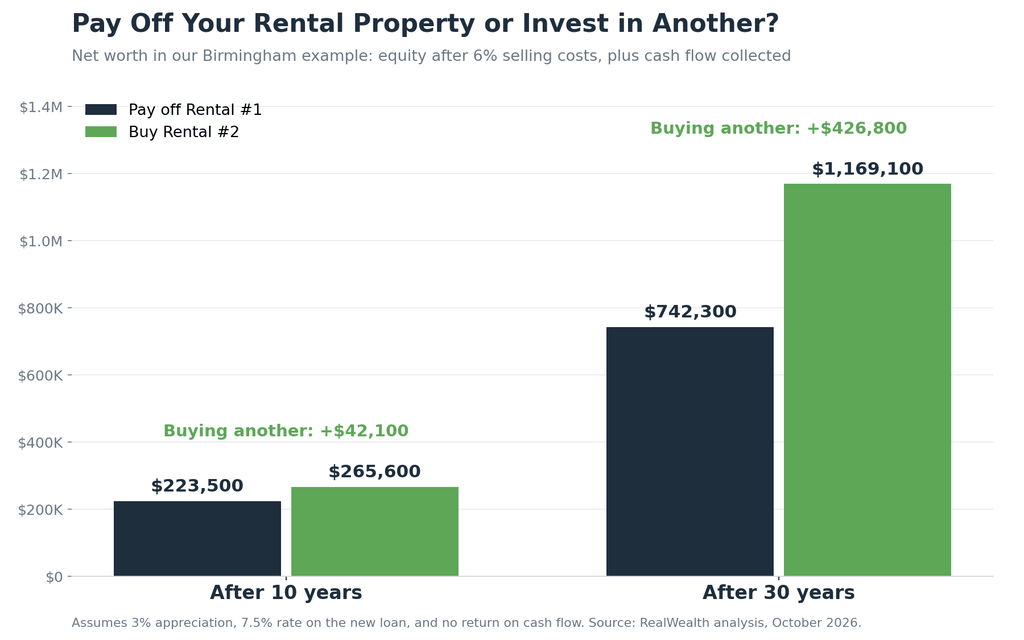
By year 10, though, buying the second rental has you about $42,000 ahead. Surprisingly, most of that difference isn’t equity. The equity numbers are fairly close at that point, since you’re still paying down two loans. The real difference is cash flow, because two rentals have been paying you every month since day one.
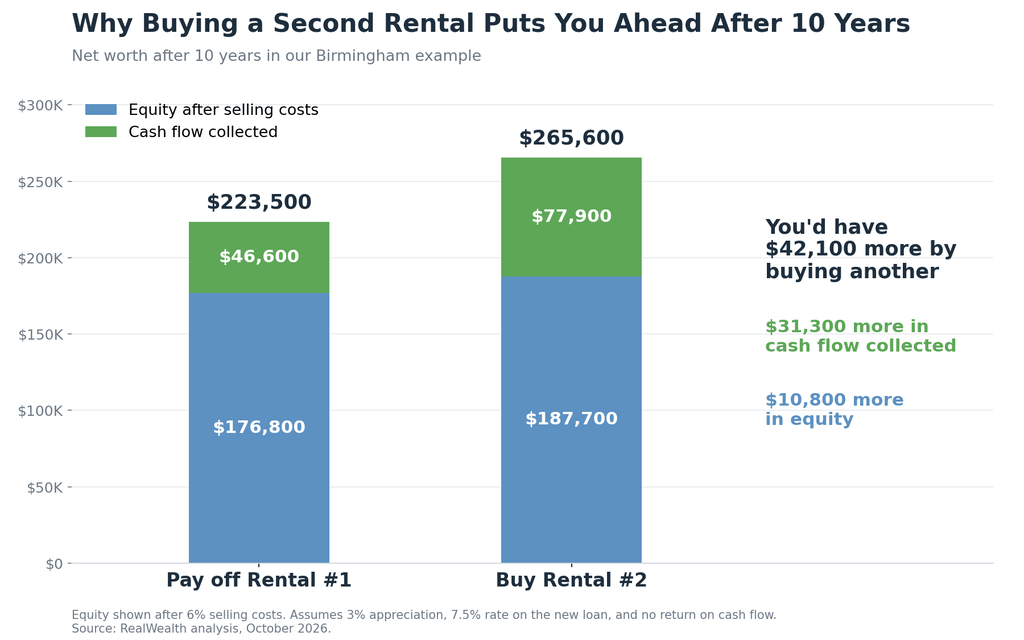
Fast forward 30 years, and both loans are paid off. Owning two rentals free and clear instead of one works out to about $340,000 more in equity and roughly $427,000 more in net worth.
So cash flow gives you the early edge. Over the long haul, the extra equity is what really adds up.
Thinking about growing beyond two rentals? Here’s how to finance multiple rental properties for maximum cash flow. Explore turnkey rental properties for sale →
What If the Market Underperforms?
Leverage cuts both ways, so we ran a tougher version too: home values grow just 1% a year, vacancy doubles to 10%, and rents rise only 2% a year.
| Pay off Rental #1 | Buy Rental #2 | |
|---|---|---|
| Monthly cash flow (year 1) | $193 | $260 |
| Net worth after 10 years | $178,900 | $176,500 |
| Net worth after 30 years | $508,100 | $700,800 |
Over the first 10 years, paying off the mortgage comes out about $2,500 ahead. With values barely moving, you aren’t building much equity on either property, and you’re still paying interest on two loans in Scenario 2. Plus, selling two properties costs more than selling one.
Stretch it to 30 years, though, and buying the second rental still pulls ahead by about $192,600. Both properties are paid off by then, and even in a slow market, two rentals bring in more than one.
This is why cash flow matters so much. In Birmingham, the second rental stayed positive even with higher vacancy, so it never cost you money out of pocket to hold it. If a property can’t cover its own costs in a rough market, that’s when paying off your mortgage starts to look a lot better.
Does the Market You Buy In Change the Answer?
Birmingham isn’t the only place this works. We ran the same numbers on four other RealWealth markets, using each one’s current prices, rents, taxes, insurance, and management fees.
How Much More You’d Have by Buying a Second Rental Instead of Paying Off the First
| Market | Monthly cash flow from both rentals (year 1) | Extra net worth after 10 years | Extra net worth after 30 years |
|---|---|---|---|
| Birmingham | +$395 | +$42,000 | +$427,000 |
| Cincinnati | +$330 | +$36,000 | +$375,000 |
| Cleveland | +$275 | +$38,000 | +$482,000 |
| Columbus, GA | +$224 | +$33,000 | +$428,000 |
| Chattanooga | +$165 | +$38,000 | +$608,000 |
The common thread? Every one of these rentals cash flows from day one. If a property won’t cash flow at today’s rates, the math gets a lot closer, especially in the first 10 years.
You might notice Chattanooga has the smallest monthly cash flow but the biggest 30-year number. That’s because homes there cost more, so the same 3% appreciation adds up to more dollars over time. Cash flow keeps the property paying for itself, and appreciation does the heavy lifting on wealth.
Most of these markets are far from where many of our investors live, and that’s by design. Our out-of-state real estate investing guide covers how to buy and manage rentals from a distance. Want more options? See our list of the best places to buy rental property.
Your financing can move the numbers, too. RealWealth investors get access to our list of trusted lenders who understand real estate investing, which makes it easier to shop for a loan that fits your plans. On top of that, many of the vetted turnkey teams RealWealth recommends offer concessions, like rate buy-downs or lower property management fees. What’s available depends on the team and changes throughout the year. For example, if you got the rate on that Birmingham rental down from 7.5% to 6.5%, you’d be about $53,000 ahead after 10 years instead of $42,000. Join RealWealth to view full proformas for available properties.
What Are the Advantages of Paying Off Your Rental Property?
Paying off a rental mortgage means more monthly cash flow, full ownership, and less pressure when a unit sits empty or a tenant stops paying. Plus, every dollar you put toward the loan saves you interest. If your rate is 6.5%, that’s like earning a risk-free 6.5% on that money. For many investors, the peace of mind of being debt-free matters just as much. For a deeper look at paying off early, read Should I Pay Off My Rental Property Mortgage?
1. More Cash Flow
Without a mortgage, rent only has to cover the property’s ongoing expenses. Whatever’s left over is yours.
Take Rental #1 from our example. With its $607 mortgage payment, it nets about $261 a month. Pay off the loan, and that jumps to roughly $868 a month from the same property.
2. Full Equity
Every payment builds equity, and a paid-off loan means you own 100% of the property. For a lot of investors, owning a rental free and clear is a milestone worth celebrating.
3. More Breathing Room During Vacancies
Even well-managed rentals sit empty between tenants now and then. With no mortgage, a vacancy costs far less, since you only cover taxes, insurance, and upkeep. That gives you time to find a quality, long-term tenant instead of rushing to fill the unit.
4. Less Stress If a Tenant Stops Paying
Good tenant screening makes evictions rare, but they can happen. With a mortgage, you’d have to cover that payment out of pocket until the issue is resolved. Falling behind and making a late payment can hurt your credit and make your next loan harder to get.
5. No Debt
For some investors, being debt-free is the goal. Personal finance author Dave Ramsey, for example, is known for telling people to avoid debt altogether, even when buying rentals. Whether it’s for peace of mind or a simpler path to retirement, owning your rentals outright can be a big relief.
If that appeals to you, here are 11 reasons to pay cash for a rental property.
6. Risk-Free Savings on Interest
Paying down your mortgage gives you risk-free savings on interest. Rental #1’s loan is at 6.5%, so every extra dollar you put toward it saves you 6.5% in interest.
If you’re not confident you can beat that elsewhere, paying it down could make sense. Just keep in mind that the money stays tied up in the property until you sell or refinance.
Is There a Downside to Paying Off Your Rental Property Early?
Yes. Paying off a rental mortgage ties up cash that’s hard to get back and gives up the leverage that helps your portfolio grow. You also lose the benefit of paying a fixed loan with dollars that are worth less over time. If a second rental would earn more than your mortgage costs, paying off early can leave money on the table.
1. Less Cash When You Need It
Once your money is in a rental, it’s not easy to get back out. If the roof needs replacing or you lose your job, your main options are selling or doing a cash-out refinance. A refinance puts you right back into a mortgage, possibly at a higher rate than before.
Before sending extra money to your lender, make sure you have a healthy cash reserve set aside.
2. Mortgage Debt Is Still Relatively Cheap Money
Rates are higher than they were a few years ago. Even so, a mortgage is still one of the least expensive ways to borrow compared to personal loans or credit cards.
On a rental, the interest you pay is generally a deductible expense against your rental income. It’s one of many tax benefits of owning rental property, and your CPA can tell you how it applies to your situation.
3. Your Equity Isn’t Working for You
Equity in a paid-off rental is real wealth, but it sits still. That same cash could go toward a down payment and help you control a whole new property.
In our Birmingham example, putting $39,200 toward a second rental instead of the first rental’s mortgage left you about $42,000 ahead after 10 years. That’s leverage at work: using a smaller amount of your own money to own a bigger asset. Join for free to compare rental property markets and opportunities →
4. Inflation Makes Your Loan Cheaper Over Time
With a fixed-rate mortgage, your payment stays the same for the life of the loan. Meanwhile, rents and home prices tend to rise with inflation, so that $607 payment on Rental #1 will feel a lot smaller 20 years from now.
As Kathy Fettke explains in Retire Rich with Rentals, “The cost of everything in life will go up, but the size of your loan payments will always stay the same.”
5. More Equity Can Make You a Bigger Target
If you’re ever sued, a property with lots of equity is a more appealing target than one with a sizable loan against it. That’s not a reason to keep debt on purpose, but it is a reason to think about protection.
Many investors hold properties in an LLC or carry umbrella insurance. Our real estate asset protection webinar covers the basics, and an attorney can help you set things up the right way.
6. A Good Rental Can Earn More Than Your Mortgage Costs
Paying off a 6.5% loan saves you 6.5% in interest, risk-free. But in every market we looked at, a second rental that cash flows from day one came out ahead, both at 10 years and at 30.
If you’re confident you can earn more than your interest rate, keeping the mortgage and growing your portfolio usually builds more wealth.
How Can You Lower Your Risk If You Keep Your Rental Property Mortgage?
Keeping your mortgage and buying another property can build more wealth, but it also means more moving parts. A few smart moves up front can protect you if the market softens or life throws you a curveball.
1. Keep Cash Reserves for Both Your Home and Your Rentals
Before you buy another property, make sure you could cover a few rough months. Your reserves should account for:
- Your personal living expenses
- The mortgage, taxes, and insurance on each rental
- Repairs and vacancies, like a new HVAC system or a unit that sits empty between tenants
Many investors keep several months of expenses on hand. If you’re financing another rental, your lender will likely want to see reserves too.
2. Choose Rentals That Cash Flow From Day One
Our numbers made this clear. In Birmingham, the second rental brought in about $134 a month after the mortgage and every expense, and it stayed positive even when we doubled vacancy to 10%.
A property that covers its own costs gives you room to breathe. One that runs short every month means you’re relying on appreciation to make up the difference, and that’s a riskier bet.
This is one reason many investors choose turnkey real estate investing. The property comes with property management in place, so you can see the numbers before you buy.
3. Lock In a Fixed-Rate Loan
With a fixed rate, your principal and interest payment never changes, while rents tend to rise over time. An adjustable-rate loan may start lower, but your payment could climb when rates do.
4. Make Sure You’re Properly Insured
The right coverage protects both your properties and your income:
- Landlord insurance policy: covers the property and your liability as an owner
- Umbrella policy: adds extra liability coverage as your portfolio grows
- Disability and life insurance: helps protect your family and your investments if you can’t work
5. Know Your Exit Options
It’s worth knowing how you’d access your money if you ever needed to. Common options include:
- Refinancing if rates come down
- Selling a property
- Using a 1031 exchange to move into a like-kind property while deferring capital gains taxes
For a deeper look, check out our guide to the 5 types of real estate investing risks.
So, Should You Pay Off Your Rental Property or Invest in Another?
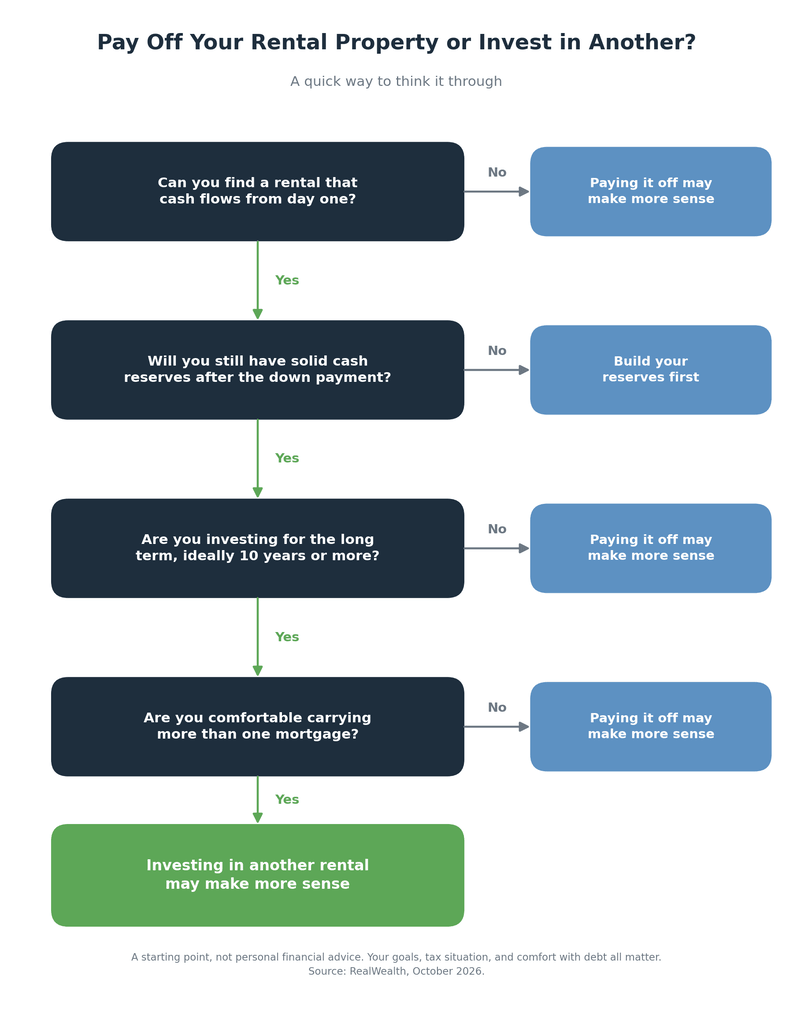
It depends on your goals, your comfort with debt, and whether you can find a rental that pays for itself. Here’s a quick way to think about it.
Buying another property may make more sense if:
- You can find a rental that cash flows from day one
- You have solid cash reserves after the down payment
- You’re investing for the long term, ideally 10 years or more
- You’re comfortable carrying more than one mortgage
Paying off your mortgage may make more sense if:
- Being debt-free is a top priority for you
- You’re close to retirement and want steady, predictable income
- You can’t find a property that cash flows at today’s rates
- Your current mortgage rate is higher than what you could reasonably earn elsewhere
Final Thoughts
Whether you pay off your rental property or invest in another one, there’s nothing wrong with owning your properties free and clear. But if you can find a second rental that covers its own costs, our numbers show it usually builds more wealth over time, even when the market underperforms.
As the saying goes, plant as many trees as you can effectively water. The key is choosing rentals that can carry themselves, and keeping enough cash on hand to ride out the occasional dry spell.
Ready to run the numbers on your next property? Join RealWealth for free to see current properties from vetted teams and talk through your goals with an investment counselor.