Live in a pricey market? Or maybe the homes you can afford just don’t excite you. Many first-time buyers are in this same situation. The traditional path means saving for years, stretching your budget, and settling for a starter home in a neighborhood you didn’t really want. But you don’t have to be stuck with this. Buying an investment property before your first home flips that order. With this strategy, you buy in markets where the numbers work, rent it out, and let tenants pay down the mortgage while you build equity.
More and more people are taking this route as high home prices and mortgage rates squeeze affordability. And there’s more than one way to make this work for you. You can follow the rentvesting model, keep renting where you live and own a rental in another market, or house hack by buying a duplex (or triplex or fourplex), living in one unit, and renting out the others.
In this article, here’s what we’ll cover:
- Why home prices and rates are pushing more first-time buyers toward rentals
- How rentvesting and house hacking work, and what each takes to get started
- The tax benefits, cash flow, and equity that make this strategy worth considering
- How your first rental can become a stepping stone to the home you actually want
Quick Answer: Is it better to buy an investment property before your first home?
It can be, especially if you’re priced out of the market you want to live in. Many first-time buyers are rentvesting instead: renting where they live and buying a rental with cash flow potential in a more affordable market. While median home prices start at $500,000 in the Northeast and West, turnkey rentals in Ohio, Indiana, and Alabama markets start around $120,000 to $220,000, making this strategy more affordable.
RealWealth helps investors build wealth with turnkey rental properties from vetted teams, with property management already in place. Join RealWealth to explore markets that fit your budget.
Reason #1: Home Prices Keep Outpacing First-Time Buyers
Home prices are still rising in most of the country, and that’s pushing many first-time buyers out of the markets where they want to live. According to the National Association of REALTORS®, prices rose in 80% of metro areas in the second quarter of 2026.
The gap between regions is where the opportunity lies:
- Median single-family prices sit at $547,200 in the Northeast and $637,900 in the West
- The Midwest median is closer to $340,800
- Turnkey single-family rentals in RealWealth’s Cleveland, Indianapolis, and Birmingham markets start around $120,000 to $220,000
That last number changes the math. Instead of saving for years to afford a down payment in an expensive metro, you could buy a rental with roughly $32,000 to $45,000 in minimum capital using 25% down financing, and start building equity now. Compare markets and see current turnkey rental properties for sale.
Reason #2: Rates Matter Less When Tenants Cover the Payment
Mortgage rates have been making it harder for people to buy a home. On a rental, though, mortgage rates hit differently, because your tenants’ rent covers most or all of the monthly payment.
Freddie Mac’s 30-year fixed average was 7.28% as of October 1, 2026. On your own home, that payment comes straight out of your paycheck. On an investment property, rent offsets it.
The rate you qualify for still comes down to a few factors:
- Down payment: investment property loans generally require 15% to 25% down, and putting more down can lower your rate
- Credit score: 740 or higher typically gets the best pricing
- Debt-to-income ratio: lenders want room in your budget after the new payment
- Cash reserves: about six months of expenses strengthens your application, and retirement accounts like a 401(k) or Roth IRA can often count toward it, though lenders may only count part of the vested balance
Start with a lender that already understands real estate investing. RealWealth’s list of trusted lenders is a good place to begin. For a full rundown of loan options, see our complete guide to financing for real estate investors.
Reason #3: Rent Where You Want to Live, Buy Where It’s Affordable (Rentvesting)
Rentvesting is a strategy where you keep renting in the area you want to live and buy a rental property in a more affordable market. With this strategy, you start building equity now instead of waiting until you can afford a home in your own neighborhood.
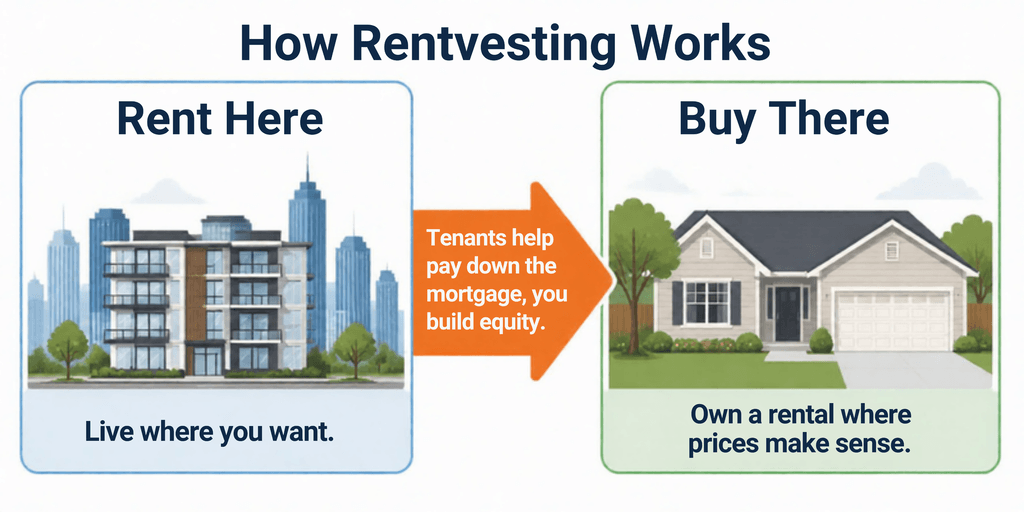
Maybe you are outpriced in your current market. Or maybe you can afford a home, but the neighborhoods you want to live in are too far from work, or the ones you can afford are not the neighborhood you’d choose. Rentvesting gives you another option:
- Keep the location and lifestyle you have now
- Own a rental in a growth market where prices and rents make sense
- Let tenants help pay down the mortgage while your equity grows
- Buy your own home later, on your timeline
This investing strategy pairs naturally with turnkey rentals. The property comes renovated or newly built, with property management already in place, so you don’t need to live nearby to own it. Not sure where to start? Here are the best places to buy rental property right now.
Reason #4: House Hacking Makes Your First Home an Investment Property
Can your first home be an investment property? Yes. With house hacking, you buy a duplex, triplex, or fourplex, live in one unit, and rent out the others. Because you live there, you qualify for owner-occupied financing with a much smaller down payment, and your tenants’ rent helps cover the mortgage.
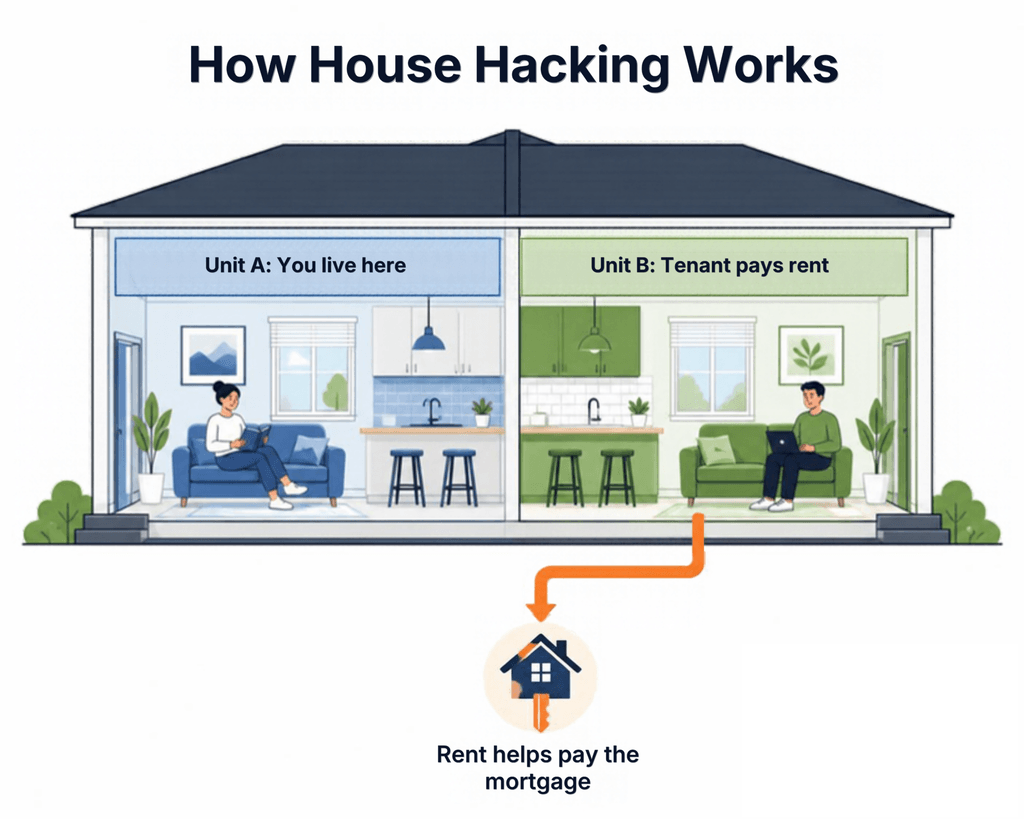
Once you’ve met the occupancy requirement, usually 12 months, you can move out and keep the whole property as a rental.
Down Payment Requirements for House Hacking
| Loan type | Units | Minimum down | What to know |
|---|---|---|---|
| FHA | 2-4 | 3.5% (580+ credit) | Live there 12 months; mortgage insurance required; 3-4 units must pass the self-sufficiency test |
| Conventional, owner-occupied | 2-4 | 5% | Stricter credit standards; PMI can be removed at 20% equity |
| Conventional, investment | 2-4 | 25% | No occupancy requirement |
On a $400,000 duplex, that’s about $14,000 down with FHA, $20,000 with a conventional owner-occupied loan, or $100,000 as a straight investment purchase, plus closing costs.
A few FHA details to know:
- You’ll pay an upfront mortgage insurance premium of 1.75%, plus an annual premium
- Loan limits vary by county, so check this FHA loan limits lookup
- Lenders can count projected rent from the other units toward your income
- For 3-4 units, the self-sufficiency test requires 75% of projected rent from all units to cover the full mortgage payment.
The catch is that you have to live there. House hacking works best if you live in, or plan to move to, a market where the numbers work. RealWealth’s property teams offer duplexes for sale in markets including Fort Worth, San Antonio, Oklahoma City, Kansas City, Wichita, and parts of Florida and Indiana. If you’re staying in a high-cost area, rentvesting with a conventional investment loan is usually the more practical route. An investment counselor can walk you through both options.
Reason #5: Flexibility in Your Lifestyle
Buying a rental before a primary residence keeps your options open. If you’re early in your career, single, or not ready to settle in one city, a mortgage on the home you live in can tie you down.
With an investment property instead, you can:
- Take a job in another city without having to sell
- Rent in a neighborhood you love, even if buying there isn’t realistic yet
- Keep building equity in a growing market, wherever you live
Owning a rental in another state is more common than you might think, especially with property management in place. Here’s how to buy real estate out of state if you’re new to it.
Reason #6: Rental Property Tax Benefits
A rental property comes with tax advantages that go well beyond what you get on your own home, and they can meaningfully boost your returns. Here are the main deductions most landlords can take:
- Mortgage interest, usually your largest deduction
- Depreciation on the building (not the land) over 27.5 years, starting the month it’s placed in service
- Repairs, deducted in the year you make them (improvements like a new roof are depreciated instead)
- Small purchases of $2,500 or less, like an appliance, under the IRS de minimis safe harbor
- Operating costs like insurance, property management fees, and legal and accounting fees
Two federal rules recently got more favorable for investors. The One Big Beautiful Bill Act permanently restored 100% bonus depreciation for qualifying property acquired after January 19, 2025. It also made the qualified business income (QBI) deduction permanent, which lets you deduct up to 20% of net rental income if your rental activity qualifies as a trade or business.
House hacking? You can only deduct expenses for the units you rent out, not the one you live in.
Tax rules depend on your situation, so talk with a CPA who works with real estate investors before you file. Start with RealWealth’s list of trusted CPAs. For a deeper look at deductions, see the top 10 tax benefits of owning rental property.
Reason #7: Cash Flow and Equity Toward the Home You Actually Want or Pay Off Debt
An investment property can help fund the home you really want as your tenants’ rent goes toward the mortgage, so you build equity as the loan balance drops and as the property appreciates over time. If rent exceeds your expenses, that extra cash flow can go toward savings, debt, or your future down payment.
When you’re ready to buy your own home, you have a few options:
- Keep it and let documented rental income strengthen your mortgage application
- Refinance to pull out equity while keeping the property
- Sell the rental and use the proceeds for your down payment (here’s how to calculate capital gains tax on investment property)
Many investors keep that first rental and add a second or third. If you’d rather sell and trade up to a larger rental, a 1031 exchange lets you defer capital gains taxes by reinvesting the proceeds into another investment property. Learn more about the power of leverage in real estate.
How RealWealth Can Help You Buy an Investment Property Before Your First Home
Buying your first rental before your first home can feel a bit daunting, especially in a market you don’t live in. RealWealth helps investors build wealth with turnkey rental properties in affordable growth markets across the country.
Since 2003, we’ve connected investors with property teams that go through 90+ days of vetting before we work with them. Many of the properties they offer meet our REAL Income Property Standards™, and properties come with property management in place, so you can own a rental without being a hands-on landlord.
When you join RealWealth, you can:
- View turnkey single-family and small multifamily rentals for sale, with full pro formas
- Talk with an investment counselor for free about rentvesting, house hacking, and financing
- Connect with trusted lenders, CPAs, and other investor-focused resources
More than 90,000 investors have joined RealWealth, and it’s free to get started. Join RealWealth today to find a market that fits your budget and goals.